Keep a complete claim file
Save letters, estimates, receipts, inventories, and written explanations. A clean file makes it easier to answer questions or challenge factual errors.
Read the policy section tied to the dispute
Match the claim issue to the covered peril, exclusion, deductible, valuation method, sublimit, or condition actually involved.
Create a claim timeline
For claim depreciation, organize the event, notice to the landlord or insurer, evidence, expenses, and claim communications chronologically.
- Loss date and time.
- Claim number and adjuster.
- Photos, receipts, and item list.
- Requests and response dates.
ACV versus replacement-cost guide
Direct answer for this situation
Actual cash value generally reflects depreciation, while replacement-cost coverage is designed around the cost of a comparable replacement subject to policy terms. Do not assume replacement-cost value is always paid up front; ask how initial payment, depreciation, replacement proof, limits, and deadlines interact.
Questions that change the answer
- How is depreciation calculated for each property category?
- Is recoverable depreciation paid only after replacement?
- What replacement deadline and documentation rules apply?
- Does the coverage limit cap payment before or after the deductible calculation?
Use a record, not memory: save the policy form or written answer that resolves each question.
Worked example
Illustration only: a comparable replacement costs $1,200, estimated depreciation is $450, and the property deductible is $500. An ACV-style starting calculation could be $250; a replacement-cost ceiling could be $700. The actual claim may differ because policy language, limits, depreciation methods, and settlement procedures control.
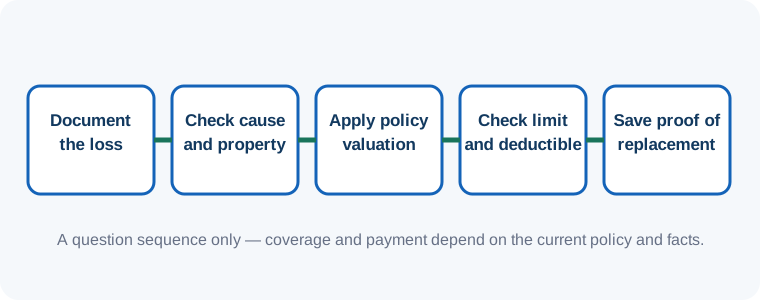
Evidence checklist for Claim Depreciation
- Original item and condition
- Current comparable replacement
- Depreciation explanation
- Initial claim payment
- Replacement invoice and submission deadline
Sources used for this guide
These sources support the general education above. The issued policy, endorsements, insurer claim communications, and facts of a loss control an individual coverage decision.
- NAIC renters insurance consumer insight — plain-language ACV and replacement-cost explanation
- NAIC post-disaster claims guide — claim valuation examples
Related Reading
Reference Sources
Use public insurance resources and your policy documents to confirm definitions, consumer contacts, and coverage limits before buying or filing a claim.